Bank Transfer Day
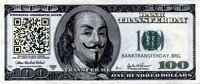
Bank Transfer Day poster: $100 bill featuring Guy Fawkes mask over Benjamin Franklin.
Last year, November 5th was designated as Bank Transfer Day as part of form of “consumer activism” … a movement started as a Facebook page calling for people to switch from using commercial banks for their financial transactions to not-for-profit organizations like credit unions.
The Facebook page was created by Kristen Christian, (one of the “Occupy Wall Street” protesters who says that her motivation was her dissatisfaction with Bank of America’s “ridiculous fees and poor customer service”), and called on supporters to effect the change by November 5th … a date chosen because of the association with Guy Fawkes; one of the participants in the “Gunpowder Plot”, a plot to blow up the British Parliament and reinstate Roman Catholic rule … and a character that has been adopted as a symbol by the Anonymous Group.
One of the results of the action was that some banks actually reduced or dropped some of their fees … also the American credit unions reported an increase in new accounts and monies deposited with them … and congress saw proposed amendments to legislation aimed at limiting the fees that banks can charge.
Now, the Banking System here in Kyrgyzstan is still fairly limited, it is developing. All the banks offer basic transaction services, (both in country and international transfers). In recent years many have introduced a variety of payment cards, (ATM Cash dispenser cards, credit cards, debit cards …), and they are attempting to introduce more traditional credit facilities, (loans and mortgages), as well as other new services such as insurance and internet banking. Many of these innovations are being supported by internationals donors such as The European Bank, (EBRD), or the International Finance Corporation, (IFC).
In addition to the equivalent of “High Street Banks” with a network of branches, there are a variety of Credit Unions and Microfinance Organizations.
Some of the banks are local but others have been set up with foreign investment. The Kazakhs have invested heavily and the EBRD have equity in and support a number of banks in the country. There are often accounts in the news about other banks interested in opening and operating in the Kyrgyz market.
Just like the High Street Banks back in the West, the Financial Institutions of Kyrgyzstan have been the subject of considerable controversy.
Currently there are a similar number of banks as there were when I first came to Kyrgyzstan, back in 1997, but only a few of them have been in operation all the time. Many of the banks that were operating back then have gone into bankruptcy or special administration. Others have been taken over and/or merged into new legal entities.
The ownership of several of the banks have frequently been the subject of rumours – tying one bank with one prominent person or another – most famously with Maksym Bakiev and there has been much speculation about different financial schemes implemented through the different banks and following the revolution of 2010 there were rumours about how much of the assets of the banking system had been removed.
In another example, in recent times an Iranian Bank which wanted to open a subsidiary here had the license refused because, or so it was claimed, the necessary detailed information about the ownership was not forthcoming.
One of the constant complaints from businessmen over the years has concerned the lack of available, (of affordable), finance.
The main controversy concerns the rates of interest charged.
One of the main problems is the amount of interest charged – which are quite high when compared to rates on the international market. As I understand it, this is partly because of the lack of available capital held by the banks to be issued as loans, and so the funding has to come from another source – international finance … which in turn means that a premium has to be charged on the rates paid by the institution itself.
Furthermore, the institution has a to charge a premium foreign currency risk – borrowing hard currency on the international market and having to pay interest in that foreign currency, whereas the loans and interest accrued in Kyrgyzstan are often in local currency.
Another of the problems used to be that the provisions of the Tax Code were such that companies were limited as to how much could be written off as an expense against profit tax – not the the full amount of interest paid … although that issue was addressed when the legislation was revised a few years ago.
Microfinance institutions, in particular, have come under considerable criticism for the high rates of interest that they have charged. In addition to the factors affecting other institutions, they are other factors such as that the loans they issue are much smaller than those offered by other institutions … may not be secured by guarantees and pledges and the fact that they have to maintain a larger network of rural offices.
That may provide an explanation as to why rates tend to be high, but it doesn’t excuse anyone from issuing misleading information – and, according to many of the protesters, some institutions are guilty of what would be considered in the West as pretty “sharp practice” … for example quoting a headline rate of interest without stating the “annual percentage rate” … which is usually – even in the West – much higher. Apparently, according to the protesters, it can be in excess of 100% per annum.
There is a continuing protest currently underway with a yurt erected in Gorky Square. Protesters are calling for the institutions to be reorganized, for greater state control. One businessman attracted their ire when he made comments in an interview to the local press that they should not expect anyone, not even the state, to come to their rescue.
There is however a new service being offered by at least one of the banks, and there is interest from the donor organizations in supporting the innovation … training in financial management.




 Bishkek
According to a recent news report … the banks account for something like 96% of the financial services in Kyrgyzstan whereas in the West the equivalent figure is much less with the “stock market” being the major provider of services – with something 60% of the market.
According to the report, Kyrgyzstan has 22 commercial banks, 15 insurance companies, 8 investment funds, 1 stock exchange, 2 pension funds, 418 microfinance organizations, 188 credit unions, 646 pawn shops (known locally as Lombards (!)), 284 exchange offices and 1 specialized loan office.
At the same time concentration level is the following: in the banking system 4 largest banks hold 55.4 percent of the market, 4 largest international financial institutions have 75.6 percent, 4 insurance companies have 46.4 percent.
State-owned banks have a wide network of branches and savings banks, and have good access to domestic and budgetary resources … “But they use them with minimal performance”.
Foreign banks, however, have an advantage in attracting money from parent companies at low interest rates.
Domestic banks accumulate funds of population and enterprises in the republic.
Microfinance organizations, it goes on to say, can be compared with commercial banks based on the size of credit portfolio.
The largest international financial institutions operate on foreign capital rather than domestic funds.
Somewhat surprisingly, the first half of 2012 showed that although the banking sector reported good profits as a whole, (1.24 billion som – that’s about 26 million dollars), some six banks suffered losses. The non-profit institutions recorded 543 million som profit (just over a million dollars); being non-profit organizations, this is channelled back into the system rather than being distributed to shareholders as dividends.